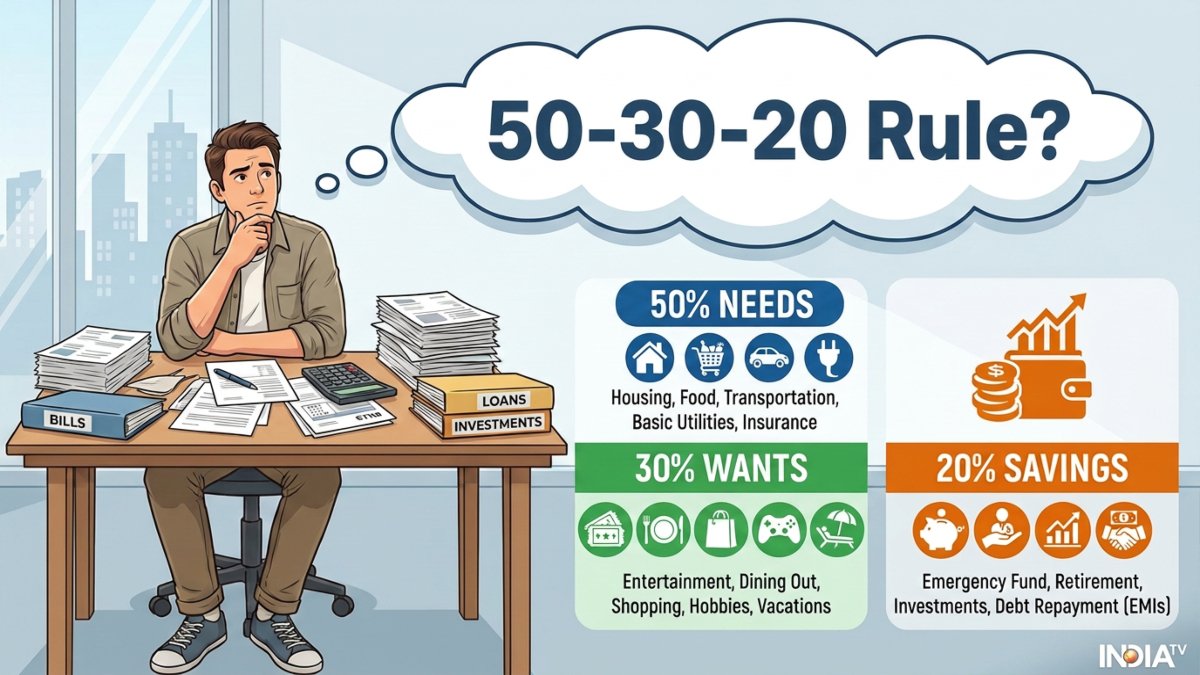

The 50-30-20 rule is a popular global framework for dividing monthly income as 50 per cent for needs, 30 per cent for wants, and the remaining 20 per cent for savings. However, financial experts say the formula, built around higher-income economies with stronger social security nets, often struggles to hold up against Indian household realities. Experts believe that instead of chasing a fixed savings percentage, Indian salaried individuals can benefit more from prioritising essential expenses, insurance, and an emergency fund before deciding how to allocate the rest of their income.
According to Akshay Gulati, Founder of Super Investing AI, the rule was never built for Indian paychecks and tends to collapse the moment real expenses enter the picture.
Why does the 50-30-20 rule often fail to fit Indian salaries and household realities?
For someone earning Rs 60,000 a month, that’s Rs 30,000 for needs. But rent alone in a metro can be Rs 20,000-25,000, leaving barely Rs 5,000-10,000 for groceries, utilities, transport and healthcare, which is mostly out-of-pocket in India, unlike in developed countries where incomes are higher and a social security net picks up some of that cost.
Also, add support for parents, a common reality in Indian households, and the “needs” bucket breaks before the month even starts. Where you live and what you earn changes everything, so one fixed rule doesn’t fit here.
Does the approach change with income level?
“The approach can be very different depending on income level”, Akshay said. Someone earning Rs 30,000 may spend Rs 25,000 on needs alone, leaving little room for savings.
For someone earning Rs 2 lakh, the situation is completely different. People in the lower-income bracket should focus on building an emergency corpus first before thinking about long-term investing. As income grows, more of it can go towards the investment corpus.
Where do EMIs fit in?
EMIs don’t need to be in a separate category. You can split them between needs and wants, depending on what the loan was taken for.
For instance, on a Rs 70,000 salary, an Rs 18,000 home loan EMI is a need, since housing is a basic requirement. But a Rs 2,500 EMI for a new phone or a holiday should count as a want. Putting EMIs in the right category gives a clearer picture of how much salary actually goes toward lifestyle.
What should replace the 50-30-20 rule?
According to experts, swapping it for another percentage rule doesn’t really solve the problem. A better approach is to follow your priorities. Essential expenses and an emergency fund come first.
“Take care of health and term insurance at the same time, since medical costs in India are mostly out of pocket, and NFHS-6 data shows nearly 40 per cent of Indian households still have no health insurance at all, leaving them fully exposed to a single hospital bill. Any high-interest debt like credit card dues should be cleared next. After that comes investing for long-term goals, and whatever is left can be used for discretionary spending,” he said.
What if you can’t save 20 per cent?
Not being able to save 20 per cent can work, because the rule shouldn’t be rigid. But that shouldn’t stop you from saving whatever you can, even if it’s only 5 or 10 per cent. If you don’t have any emergency savings yet, build an emergency fund first. Once that’s in place, you can start investing towards longer-term goals.
Does allocation change with age?
“Salary allocation changes continuously with different ages and life stages. At 25, someone can put more towards an emergency fund and investments”, Akshay said.
At 35, the same person may have other responsibilities that limit how much they can invest. At 55, they’ll be focused on building a retirement corpus that can support their lifestyle. So as age and income change, the allocation changes too.
How should you handle a salary hike?
A salary hike should ideally increase your investment surplus, not just your lifestyle. Say your salary rises by Rs 8,000 a month: a practical approach is to direct around 40 per cent of that, roughly Rs 3,200, towards investments before planning any lifestyle upgrade, and use the rest for discretionary spending. This way, your savings rate keeps improving with every hike, instead of expenses quietly rising to match it.
What role do family responsibilities play?
Family responsibilities play a major role in determining your savings rate. Someone supporting parents, children or other dependents may only be able to save a small percentage and still be financially disciplined.
The goal should be to balance family obligations with savings and investments, rather than chasing a fixed savings target.
Is there a danger in following any rule too rigidly?
If we simply replace one rigid rule with another, we’re not really solving the problem. Any percentage-based framework becomes counterproductive if you treat it as a law rather than a guide.
A job loss, medical expenses, marriage or a home purchase can shift your priorities from increasing savings to managing liquidity. Experts believe a good framework should build discipline while also giving you flexibility, and the formula should adapt to your life, not the other way around.
ALSO READ:
Move beyond SIPs: Expert explains how to diversify into fixed income and gold