
Concentration rarely arrives as a deliberate decision; instead, it arrives disguised as success – a winning stock doubles, employee shares accumulate, or inherited holdings stay untouched, and a good investment quietly becomes the largest risk to a family’s financial security. According to Hemant Sood, Founder and Managing Director, Findoc Group, the question is not whether the company is good, it is how much damage it can do if the thesis fails.
Hidden risks of a concentrated portfolio
Consider an illustrative Rs 1 crore portfolio with 30 per cent in one stock. A 50 per cent fall in that holding erases Rs 15 lakh, or 15 per cent of the portfolio, with everything else unchanged. Recovering that loss then requires a 17.6 per cent gain. A familiar company can still create an unfamiliar setback.
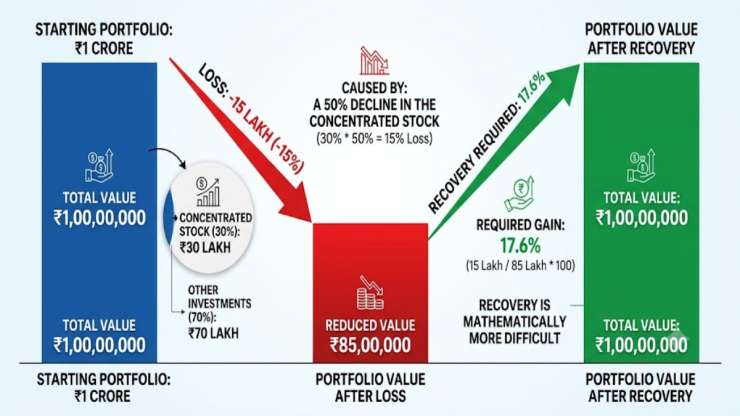
An illustrative Rs 1 crore portfolio with 30% in one stock.
“India offers reminders. HDFC Bank fell 8.44 per cent on January 17, 2024, after its quarterly results, while the Nifty 50 lost 2.09 per cent, according to a report. Paytm’s listed parent, One97 Communications, lost about 42 per cent over three sessions through February 5, 2024, after RBI restrictions on Paytm Payments Bank. Different risks, but both show how fast one holding can hurt,” Sood said.
Concentration also raises the risk of missing the rare winners. Hendrik Bessembinder’s research on US stocks from 1926 to 2016 found that roughly 4 per cent of companies accounted for the market’s entire net wealth creation above Treasury bills. Owning only a handful of companies can leave an investor outside the stocks that drive long-term returns.
How professionals manage concentration limits
Professionals already live with a limit. SEBI does not allow a diversified mutual fund to hold more than 10 per cent of its net assets in one company’s shares.
“For a typical retail investor, I would use 5 per cent of the total financial investment portfolio as a starting limit for one company, with a formal review above 10 per cent. Exposure beyond 20 per cent deserves a deliberate reduction plan. Adjust these for goals, liquidity and loss tolerance,” he added.
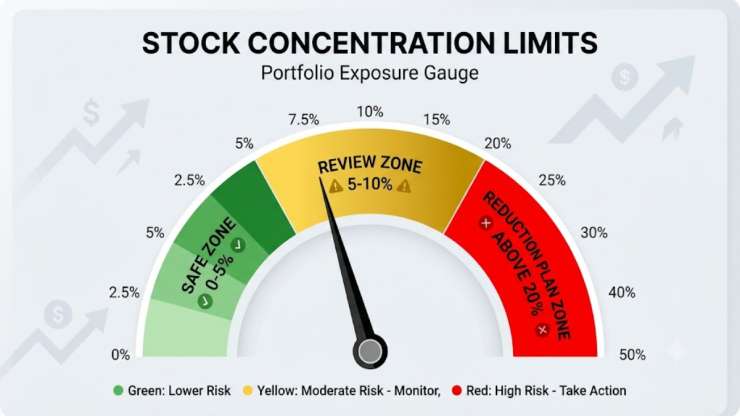
A better personalised limit starts with the loss you can absorb.
A better personalised limit starts with the loss you can absorb. If one stock should cost you no more than 3 per cent of your portfolio under an assumed 50 per cent decline, its maximum weight is 6 per cent: 3 per cent divided by 50 per cent. That decline is a stress scenario, not a floor. A fragile or illiquid business warrants a smaller position.
Hidden overlap across holdings
According to Sood, one must measure exposure using current market values across financial investments, excluding the home and operating business.
Include direct shares, mutual funds, ETFs and managed portfolios. An 8 per cent direct holding plus a 20 per cent fund allocation that holds 5 per cent in the same stock adds up to 9 per cent.
Look beyond individual names, too. Five banking stocks remain exposed to one credit cycle. Employees holding large employer stakes face a sharper version of the problem: salary and savings can fall together. Entrepreneurs should ask whether listed holdings duplicate risks already embedded in their operating business.
“Concentration can grow without another purchase. A stock that starts at 10 per cent becomes 18.2 per cent if it doubles while the rest stays unchanged. Review weights quarterly, after sharp moves, and immediately if governance deteriorates. Direct fresh savings elsewhere and trim oversized holdings against a written target, mindful of taxes and liquidity. Stop-loss orders cannot guarantee an exit price during gaps or thin trading,” he concluded.
ALSO READ:
Rs 1 crore in mutual funds? How much can you withdraw every month without running out of money?